Fourteen carriers.One best rate.
Lanewise is an independent auto-insurance distributor: one three-minute application, rated across a panel of A-rated carriers, bound the same day — with a licensed advisor on your side, not a call center. Average first-year savings: $642.
Free · No spam calls · No credit-score impact
Your carrier has one price. We make them compete.
Since 2016 we’ve put every driver’s profile in front of the whole panel at once — because the spread between carriers for the same driver is routinely 40% or more. If we can’t beat your rate, we’ll say so.
- $0Average first-year savings
- 0A-rated carriers on the panel
- 0K+Drivers covered nationwide
- 0 minMedian time, quote to bound
Every form in the book.
- Form LW-01
Liability
Bodily-injury and property-damage liability quoted across the panel — with an advisor who will show you what 25/50/25 really buys before you bet your savings on it.
Read the form → - Form LW-02
Collision & Comprehensive
Collision and comprehensive with deductibles tuned to your actual cash position — plus gap coverage when the loan is bigger than the car.
Read the form → - Form LW-03
Uninsured & Underinsured Motorist
UM/UIM steps in when the at-fault driver has no insurance — or nowhere near enough. It is the most underbought coverage in the book, and often the cheapest to fix.
Read the form → - Form LW-04
Usage-Based & Pay-Per-Mile
Telematics and per-mile programs from every carrier that offers one — with an honest read on who actually saves, and who should never plug in.
Read the form → - Form LW-05
Rideshare & Delivery
Rideshare endorsements and gig-driver policies that close the Period 1 gap your personal auto policy silently excludes.
Read the form → - Form LW-06
Commercial Auto & Fleet
Commercial auto for contractors, couriers and fleets — hired & non-owned, cargo, and per-vehicle telematics consolidated under one renewal date.
Read the form →
Quote to covered in four moves.
Quote
One three-minute application — vehicle, drivers, history. No credit-score impact, no spam-call resale. Ever.
Match
The rating engine prices your profile across the carrier panel; a licensed advisor sanity-checks limits and flags the gaps carriers hope you won’t ask about.
Bind
Pick the winner, e-sign, and you’re covered — ID cards on your phone the same day. We handle cancelling your old policy and chasing the refund.
Drive
Sixty days before every renewal we re-shop the panel automatically. If a claim happens, a former adjuster works your file until the number is right.
What a distributor does that an agent can’t.
01One application, the whole panel
A captive agent can only sell you their carrier. We rate your profile across fourteen — the quote you see is the one that actually won.
02Licensed advisors, not a call center
Every policy is reviewed by a licensed advisor before you sign. Ask them anything — limits, exclusions, that letter your carrier sent. They answer in plain English.
03We re-shop every renewal
Loyalty is how carriers raise rates quietly. Sixty days before renewal, our engine re-rates your policy across the panel — if someone beats it, you hear from us first.
04In your corner at claim time
We don’t pay claims — your carrier does. But our claims advocates, all former adjusters, make sure the settlement math holds up before you accept it.
Savings found. Claims defended.
Recent entries from the outcomes ledger. Savings figures shown are illustrative of individual client outcomes and averages across recent clients who switched; they are not a guarantee of your result. Your premium depends on your driving record, vehicle, location, coverage selections, and other rating factors.
- $18,400
Hail total-loss first offered at $14,100 — settled at the car’s real market value
Tom pulled six local comps the desk adjuster’s software ignored and re-opened the valuation. Paid in six days.
- $42,000
Hit by an uninsured driver — the UM limits we’d insisted on paid for surgery and lost wages
The client had almost waived UM to save $9 a month. The at-fault driver carried nothing at all.
- $8,400/yr
HVAC contractor’s twelve-van fleet, quoted by one agent for nine years
The incumbent had never marketed the account. Four carriers quoted; the winner came in 31% under renewal.
- $1,284/yr
Westerville family, nine years loyal to one carrier — same limits, same deductibles
Loyalty pricing had crept 9% a year. Identical coverage across the panel came back $107 a month lower.
Fourteen carriers, scored quarterly.
Quote share, claims satisfaction, renewal behavior — published, carrier by carrier.
- A+Meridian MutualPreferred multi-car households17%quote share41states2016appointed
- ABlue HarborBundles & home+auto14%quote share38states2016appointed
- ACardinal NationalClean-record value pricing12%quote share45states2017appointed
- A−Drivewell DirectTelematics & pay-per-mile11%quote share29states2018appointed
- AHalcyon AutoNew vehicles & EV replacement9%quote share33states2019appointed
- A−Keystone IndemnityYouthful drivers & good student8%quote share27states2018appointed
Licensed humans, on the record.
Underwriters, adjusters and brokers who switched sides. Every policy gets an advisor’s eyes before it binds.
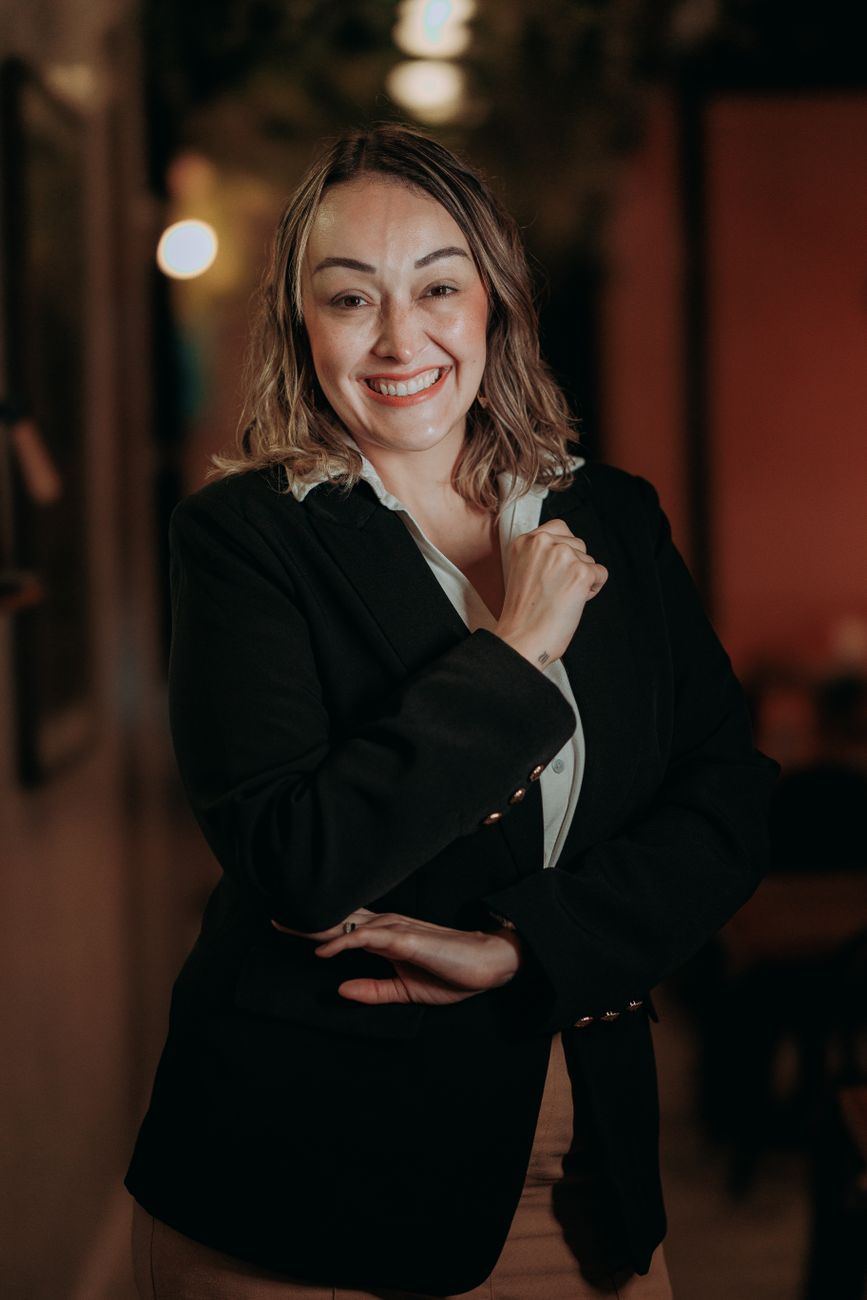
Maya Brooks
Co-founder · Principal Advisor
A former carrier underwriter who got tired of watching loyal customers subsidize new ones, Maya co-founded Lanewise to put the rating spread in the driver’s favor.
P&C — Ohio (resident) + 27 non-resident states
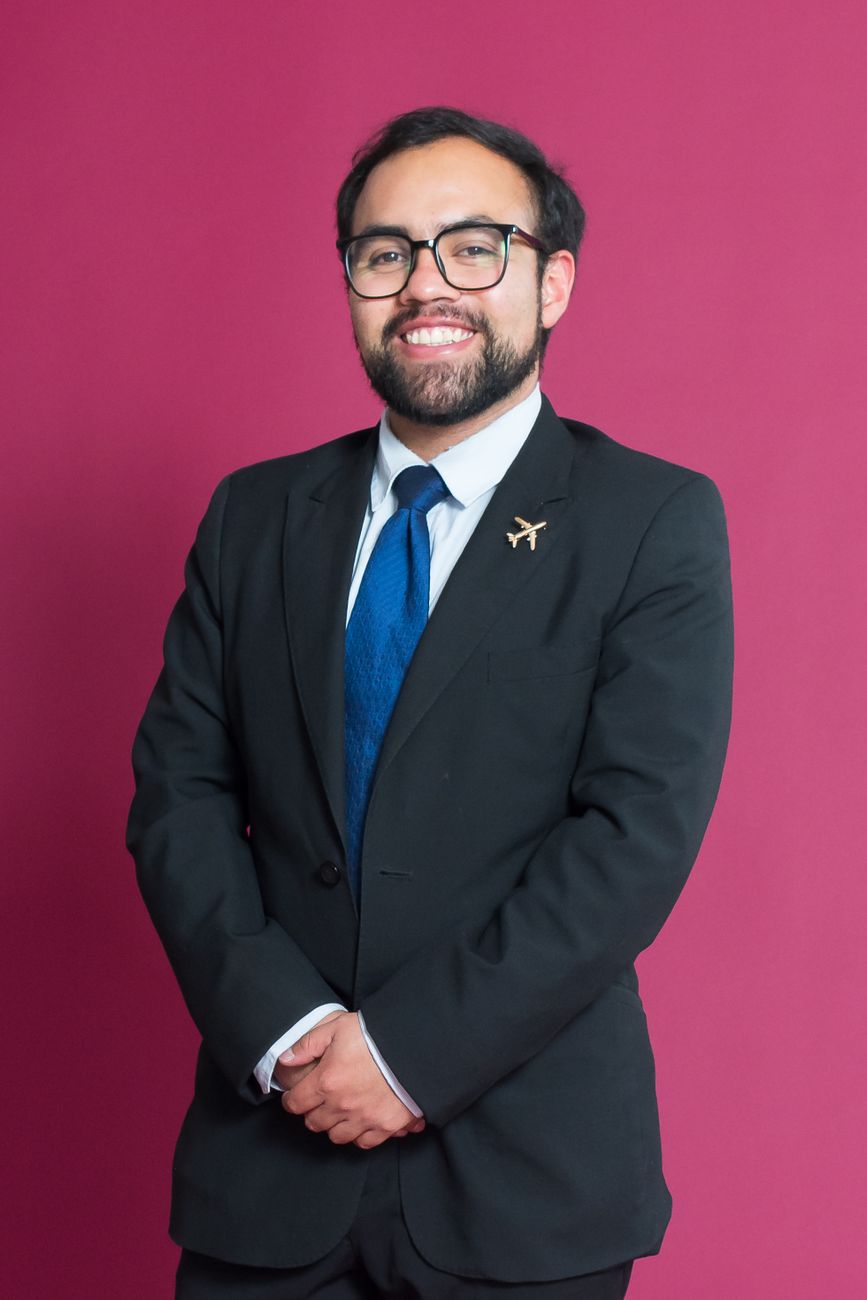
Daniel Reyes
Co-founder · Carrier Partnerships
Daniel built the fourteen-carrier panel — and keeps every carrier on it honest by measuring how they quote, pay, and renew.
P&C — Ohio (resident) + 24 non-resident states
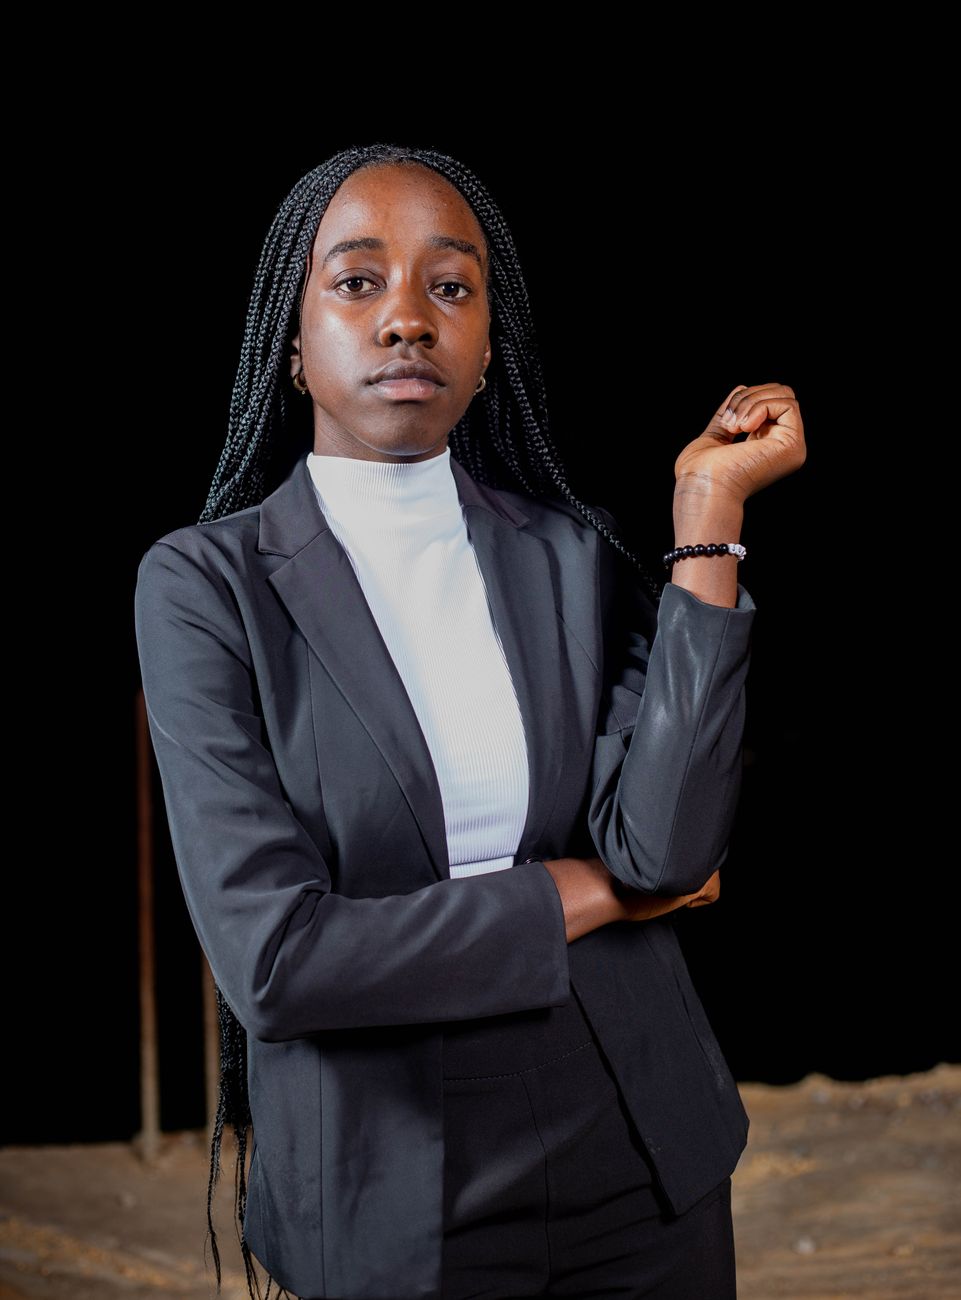
Grace Okoye
Senior Advisor · Gig & Commercial
Grace runs the rideshare and fleet desks — the risks most agencies quote wrong or won’t quote at all.
P&C — Ohio (resident) + 21 non-resident states
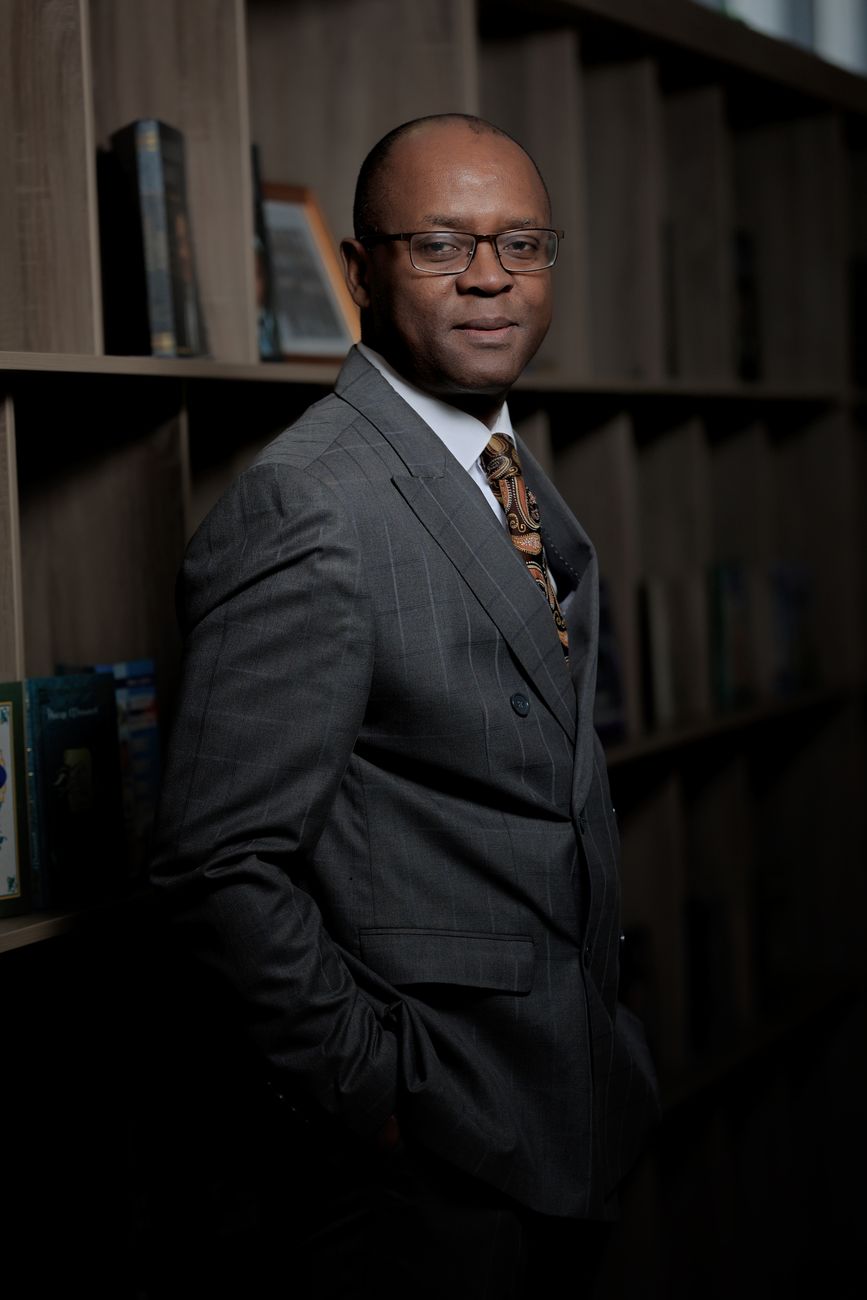
Tom Varga
Claims Advocate
Twenty years an adjuster; now he sits on your side of the table and checks the settlement math.
P&C — Ohio
What switching feels like.
“Same coverage I had for nine years, $107 a month cheaper. I kept waiting for the catch — the catch was that my old carrier was pricing my loyalty. Maya showed me the spread on one screen.”
“An uninsured driver ran a light and totaled my car. The UM coverage Daniel talked me into — that I almost declined to save $9 — paid for my surgery. I will never shop insurance by price alone again.”
“Three agencies told me they “don’t do Uber.” Grace quoted my endorsement in twenty minutes and explained Period 1 better than the platform’s own help pages. Every gig driver should hear that talk.”
Testimonials reflect the experience of individual clients, used with consent, and are not a guarantee of any future result or savings.
What the record says about us.
Drawn from our verified Google profile, public commentary on X, and the industry lists that track distributors. Reproduced here for illustration.
- InsurTech 100Listed 2023–2025
- Ohio Inc. Fast 50#11 — 2025
- InsureTech ConnectMain-stage speaker
- Trusted ChoiceMember agency
- BBBA+ · Accredited 2017
 ♥ 486
 ♥ 743
 ♥ 529
Social posts, review excerpts, follower counts, and list recognitions shown above are illustrative placeholders for this template and are not verified. Testimonials reflect the experience of individual clients, used with consent, and are not a guarantee of any future result or savings.
Straight answers, no fine print.
- Coverage
25/50/25 is not a plan: what state-minimum coverage actually buys
Ohio’s minimum limits haven’t moved since 2013. Medical bills and car prices have. Here’s the honest arithmetic on what the cheapest legal policy leaves exposed.
- Pricing
Telematics, honestly: who saves with a driving app — and who shouldn’t plug in
Carriers advertise the discount, never the surcharge. A former underwriter explains how the scoring actually works and which drivers come out ahead.
- Claims
The total-loss playbook: getting paid what your car was actually worth
A former adjuster on the valuation software, the comps it conveniently misses, and the two emails that most often move a settlement.
Make fourteen carriers compete for your renewal.
Free · 3 minutes · No spam calls. One application. The whole panel. A licensed advisor on the result.