State minimum keeps you legal. It rarely keeps you solvent.
Bodily-injury and property-damage liability quoted across the panel — with an advisor who will show you what 25/50/25 really buys before you bet your savings on it.
The coverage, decoded.
Liability pays the other side when an accident is your fault — their car, their medical bills, their lost wages. Ohio’s minimum is $25,000 per person, and the average new car costs nearly twice that. Our advisors price three limit tiers side by side so you can see what stepping up actually costs per month (usually less than a streaming subscription) before you choose. Because we rate every carrier on the panel at once, higher limits often land within dollars of the minimum-limit quote you were about to accept.
What this line includes
What the panel does for liability coverage.
01
Three limit tiers quoted side by side — see the real monthly delta before choosing.
02
Non-standard and SR-22 markets on the panel for drivers other agencies turn away.
03
Advisors licensed in 28 states who explain limits in plain English.
Outcomes on this line.
- $936/yr
Adding a 16-year-old doubled the renewal — until we moved carriers
Good-student discount plus a carrier that rates teens on the household’s telematics, not the class average.
- $624/yr
Post-DUI SR-22 filing — placed in a non-standard market instead of a punitive standard one
Two carriers on the panel actually want this risk. The one his old agency quoted does not.
Savings figures shown are illustrative of individual client outcomes and averages across recent clients who switched; they are not a guarantee of your result. Your premium depends on your driving record, vehicle, location, coverage selections, and other rating factors.
The advisors on this line.
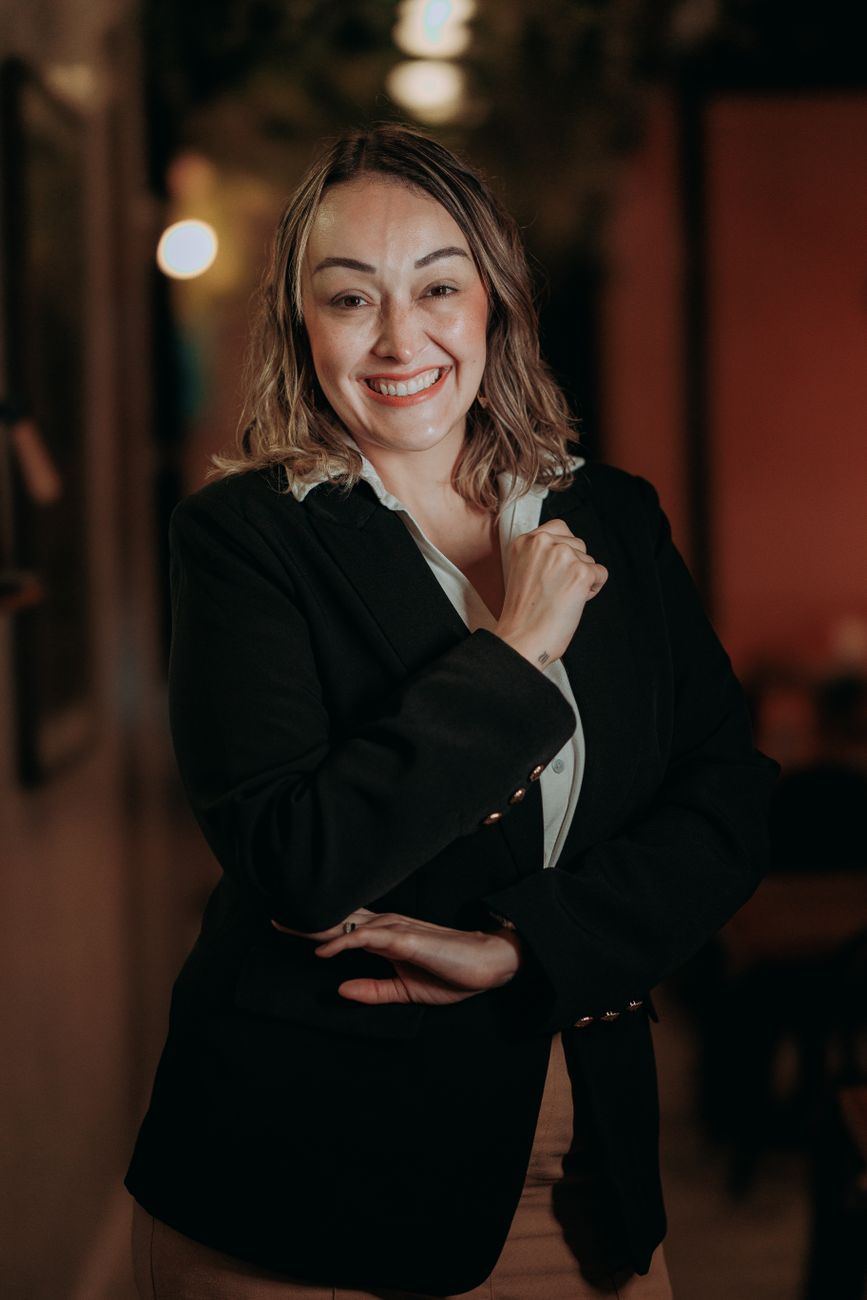
Maya Brooks
Co-founder · Principal Advisor
A former carrier underwriter who got tired of watching loyal customers subsidize new ones, Maya co-founded Lanewise to put the rating spread in the driver’s favor.
P&C — Ohio (resident) + 27 non-resident states
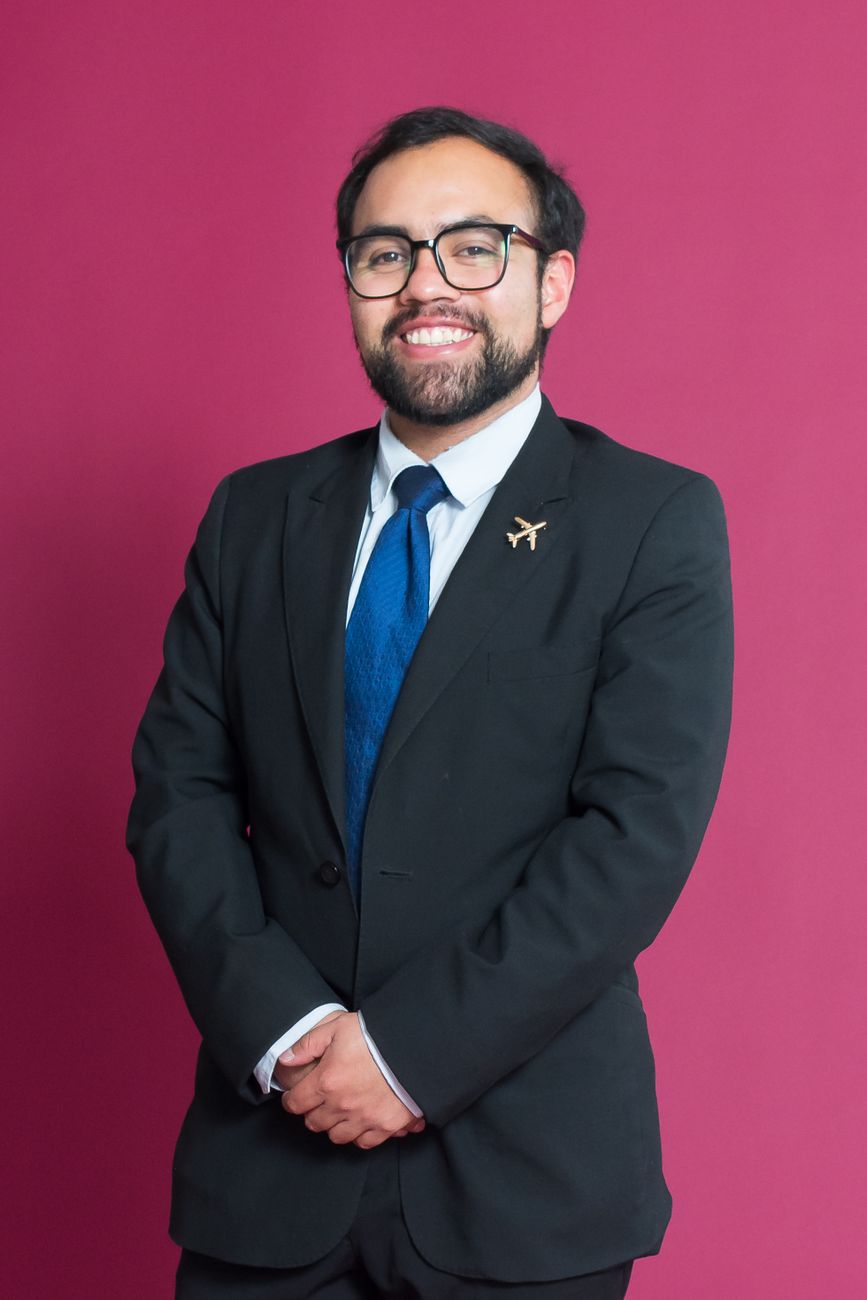
Daniel Reyes
Co-founder · Carrier Partnerships
Daniel built the fourteen-carrier panel — and keeps every carrier on it honest by measuring how they quote, pay, and renew.
P&C — Ohio (resident) + 24 non-resident states
Asked at this desk, often.
Nothing. Like every independent agency, we’re paid a commission by the carrier you choose — it’s built into the premium whether you buy through a distributor, a captive agent, or the carrier’s own website. The rate is the same either way; the difference is that we shop fourteen carriers for it and a captive agent shops one.
No. Carriers use a “soft pull” insurance score for rating, which never affects your credit score and doesn’t appear to other lenders. One application with us rates across the whole panel — it does not generate fourteen separate inquiries. And we don’t resell your information, so quoting won’t summon a plague of spam calls.
More than the state minimum, almost always. Ohio’s 25/50/25 minimum hasn’t moved since 2013 while medical costs and car prices have; one ER visit can exhaust it. Our baseline recommendation is 100/300 bodily injury with matched uninsured-motorist limits — and we’ll show you the real monthly difference for your profile, which is usually far smaller than people fear.