The other driver’s insurance won’t fix your car. This does.
Collision and comprehensive with deductibles tuned to your actual cash position — plus gap coverage when the loan is bigger than the car.
The coverage, decoded.
Collision pays to repair your car after a crash regardless of fault; comprehensive covers everything that isn’t a collision — hail, theft, vandalism, flood, and Ohio’s infamous November deer. The lever that matters is the deductible: we price $250 / $500 / $1,000 across the panel and show you the break-even math instead of defaulting you into the most expensive row. Financing or leasing? We’ll quote gap coverage at the same time — often a third of what the dealership charges for the same protection.
What this line includes
What the panel does for full coverage coverage.
01
Deductible break-even math shown per quote — not a default you discover at claim time.
02
Gap coverage quoted alongside, usually far below the dealership F&I price.
03
Claims advocates who check the total-loss valuation before you accept it.
Outcomes on this line.
- $18,400
Hail total-loss first offered at $14,100 — settled at the car’s real market value
Tom pulled six local comps the desk adjuster’s software ignored and re-opened the valuation. Paid in six days.
- $1,284/yr
Westerville family, nine years loyal to one carrier — same limits, same deductibles
Loyalty pricing had crept 9% a year. Identical coverage across the panel came back $107 a month lower.
Savings figures shown are illustrative of individual client outcomes and averages across recent clients who switched; they are not a guarantee of your result. Your premium depends on your driving record, vehicle, location, coverage selections, and other rating factors.
The advisors on this line.
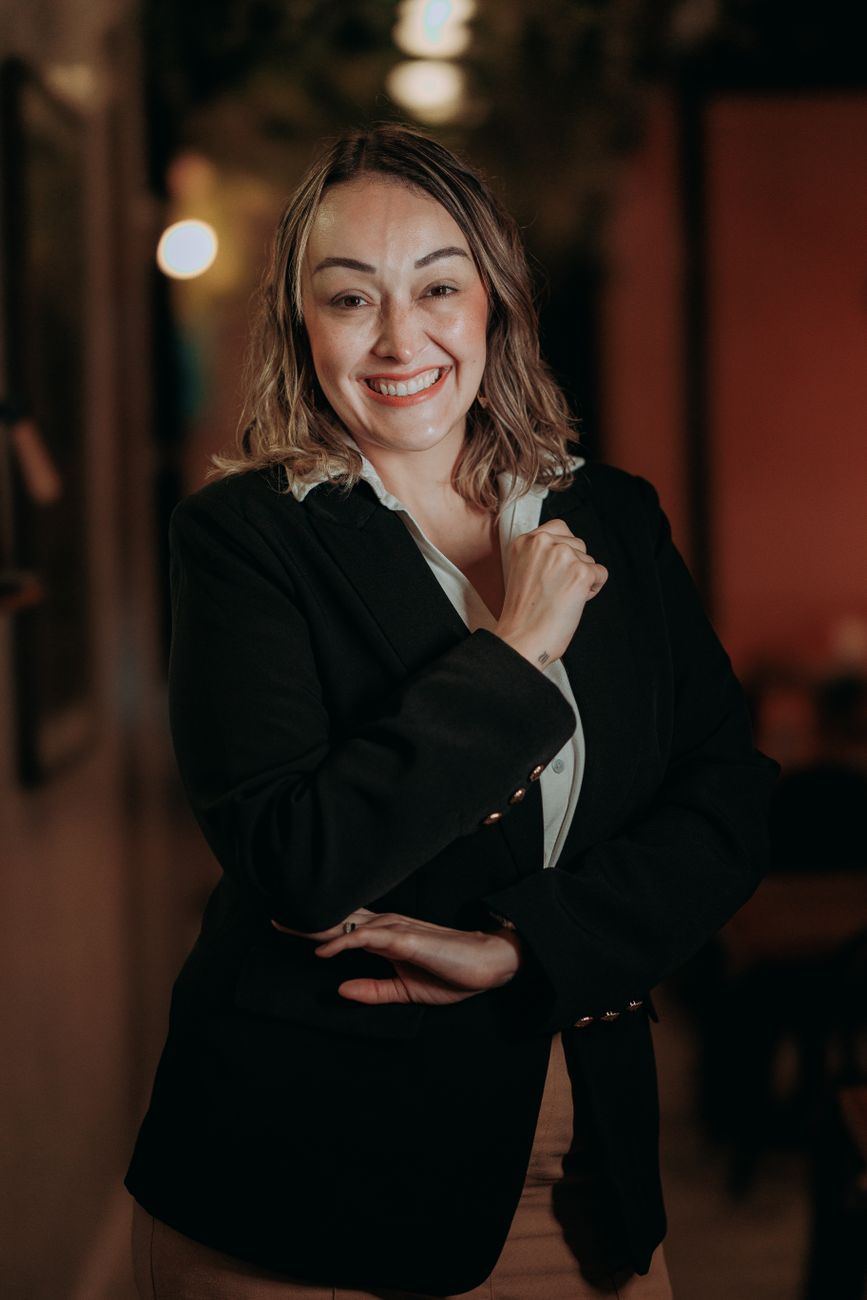
Maya Brooks
Co-founder · Principal Advisor
A former carrier underwriter who got tired of watching loyal customers subsidize new ones, Maya co-founded Lanewise to put the rating spread in the driver’s favor.
P&C — Ohio (resident) + 27 non-resident states
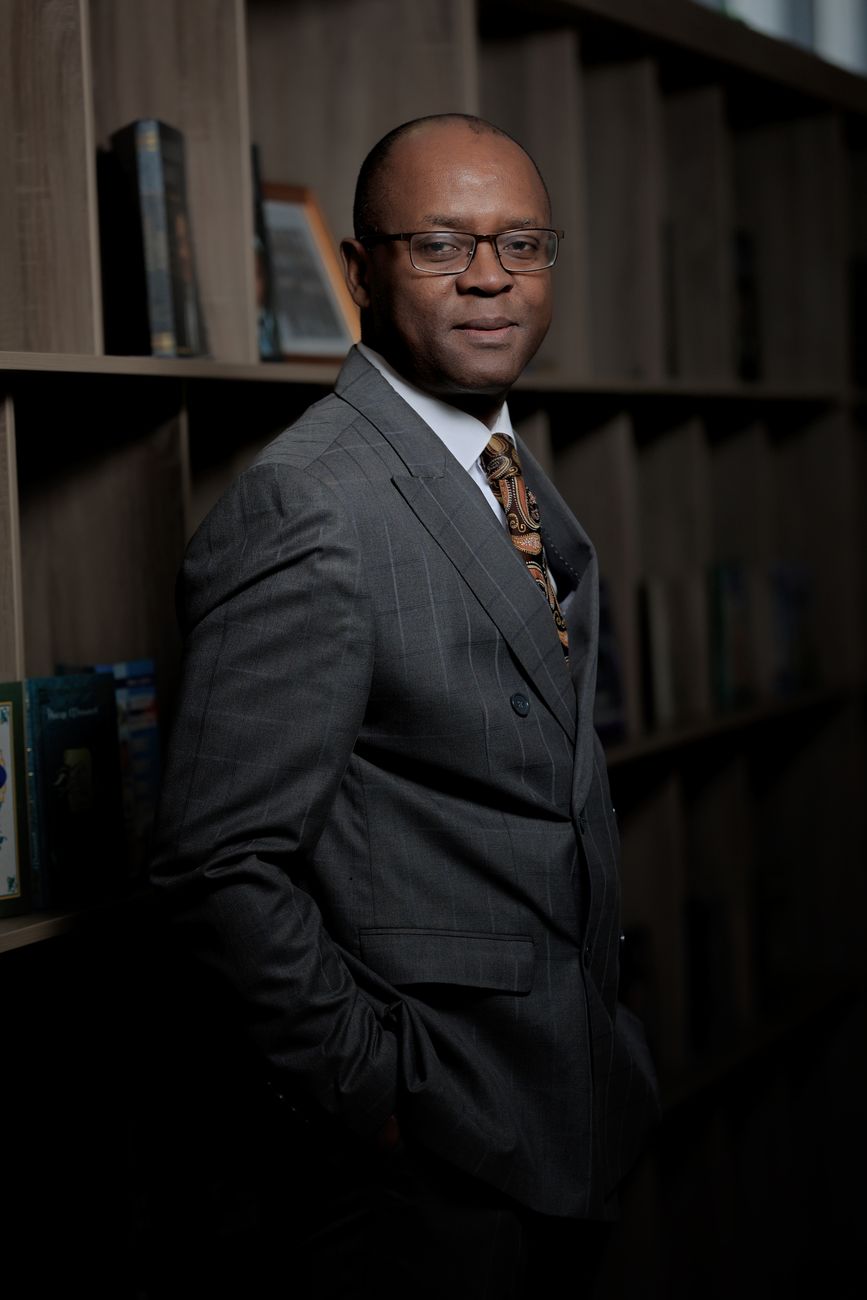
Tom Varga
Claims Advocate
Twenty years an adjuster; now he sits on your side of the table and checks the settlement math.
P&C — Ohio
Asked at this desk, often.
No. Carriers use a “soft pull” insurance score for rating, which never affects your credit score and doesn’t appear to other lenders. One application with us rates across the whole panel — it does not generate fourteen separate inquiries. And we don’t resell your information, so quoting won’t summon a plague of spam calls.
The engine surfaces every carrier’s price for your exact profile; your advisor then weighs the things a price can’t show — claims satisfaction scores, how the carrier behaves at renewal, whether they’re strong for your specific risk. Our carrier scorecard is public on the carriers page. We recommend the best fit and show you the runners-up, and the choice is always yours.
Your carrier pays the claim; we make sure it’s paid right. File with the carrier (or call us and we’ll do it together), and our claims advocate — a former adjuster — reviews the valuation and the estimate before you accept anything. If the number is light, we push with comps and documentation. That advocacy is included, for every client, always.